Your insurer makes the final coverage decision. Ask your adjuster to confirm your policy’s terms before relying on any general guidance.
What is usually covered—and what may not be
Policies commonly treat crime scene or trauma cleanup as part of restoring a property after a covered event. The work may be described as biohazard remediation, specialty cleaning, or property restoration rather than “crime scene cleanup.”
Often considered
- Professional assessment of affected areas
- Blood and biohazard removal
- Cleaning, disinfection, and odor treatment
- Removal of contaminated porous materials when necessary
- Regulated packaging, transport, and disposal
- Limited repairs tied directly to covered remediation
May be limited or excluded
- Work unrelated to the covered incident
- Pre-existing contamination or deferred maintenance
- Upgrades beyond restoring the property
- Losses excluded by the specific policy
- Building damage under a renter’s personal-property policy
- Costs above policy limits or outside approved scope
For renters, the tenant’s policy may address personal belongings or additional living expenses, while the property owner’s policy may address the structure. The two insurers may need to coordinate.
How the claims process works
You do not need to become an insurance expert before asking for help. A clear sequence—and good documentation—makes the process easier to manage.
- Protect people and restrict access.
Do not enter or disturb an affected area. Wait until law enforcement has released the scene, when applicable.
- Report the loss promptly.
Call the claims number on the policy and explain that professional biohazard remediation may be needed. Ask for the claim number and adjuster’s contact information.
- Request a professional assessment.
The cleanup company should inspect the property, define the affected area, and prepare a written scope rather than offering an unsupported phone quote.
- Document conditions before work begins.
When permitted, the contractor should record the affected materials and necessary remediation without sharing sensitive scene images more widely than needed.
- Confirm the communication path.
Ask whether the insurer wants the estimate sent directly to the adjuster and whether any authorization is required before non-emergency work proceeds.
- Complete remediation and submit records.
After the work, the contractor should provide an itemized invoice, disposal records, and completion documentation for the claim file.
The documentation your cleanup company should provide
A well-supported file gives the adjuster a clear explanation of what was affected, why each step was necessary, and what was completed.
Claim documentation checklist
- Written estimate and defined scope of work
- Itemized labor, materials, and disposal charges
- Condition photos, handled with discretion
- Notes identifying affected materials and rooms
- Waste transport or disposal documentation
- Completion report or service summary
- Contractor insurance information when requested
- Copies of signed work authorizations
Keep your claim number on every document. Save copies of emails, names, dates, and decisions. If the adjuster gives instructions by phone, send a brief written recap so the claim file reflects what was discussed.
Three claim problems to avoid
Hiring an uninsured contractor
An uninsured provider can create liability concerns and may not supply the records an adjuster expects. Ask for proof of insurance before authorizing work.
Delaying the report
Waiting can allow contamination or odor to spread and makes it harder to separate the original loss from later damage. Notify the carrier as soon as reasonably possible.
Submitting poor documentation
A vague invoice does not show why the work was necessary. Use a provider that records the scope, affected materials, work performed, and disposal path.
What about the deductible?
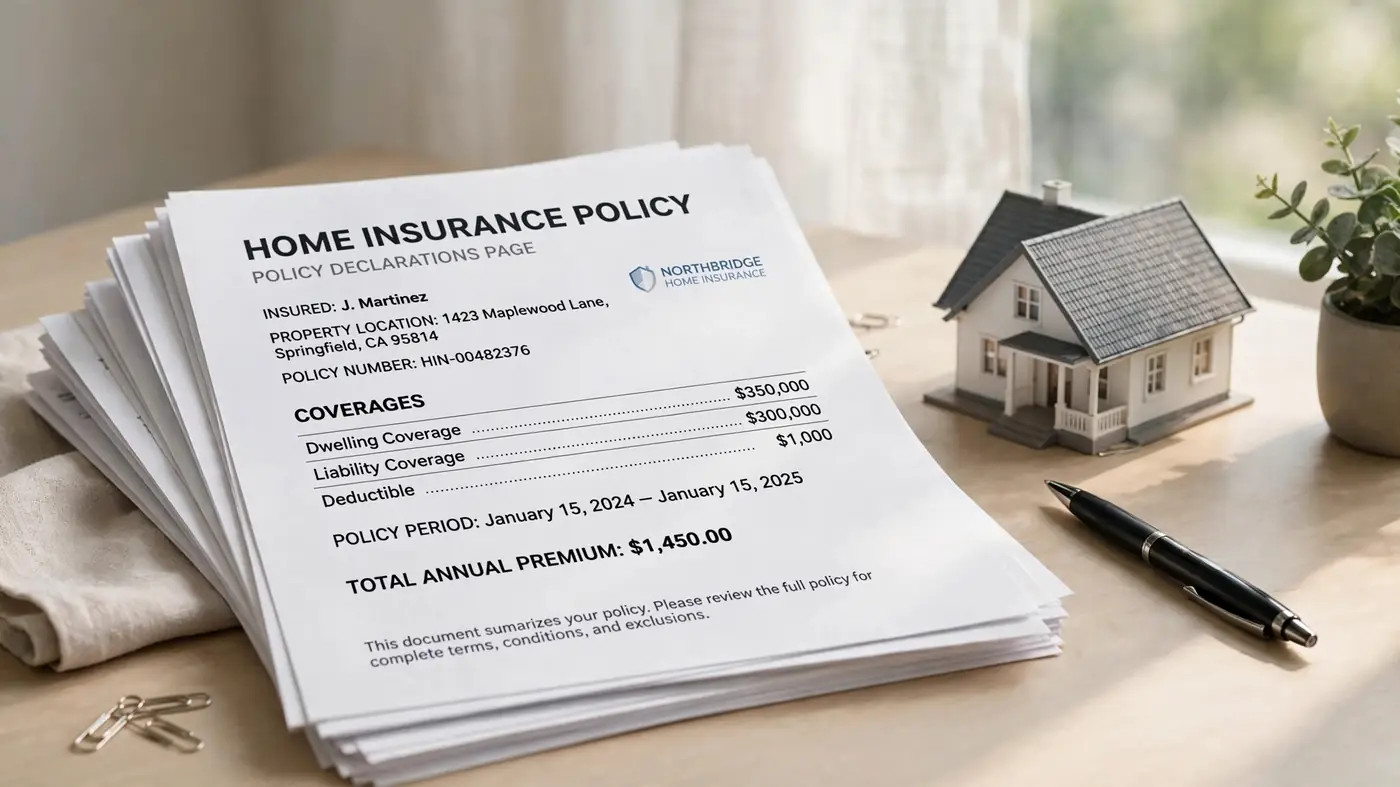
You handle the policy deductible; we document the rest.
If the loss is covered, you are generally responsible for the deductible listed in your policy. We can prepare the written scope and supporting records your adjuster needs to review the remaining covered work. The insurer—not the cleanup company—determines what is payable.
Need help documenting a cleanup claim?
Call BioRecoveryUSA for a discreet assessment and written estimate. We can organize the remediation records for your insurer while you focus on the next step.